Life Insurance for Grandparents: Final Expense Coverage
Life insurance for grandparents final expense coverage protects grandchildren from funeral bills. Call (833)-212-4240 to compare affordable plans.
By Olivia Ingram
When a grandparent passes away, the last thing a grieving family should worry about is how to pay for a funeral. Yet the average funeral in the United States now costs between $7,000 and $12,000, and that figure climbs higher when you add burial plots, headstones, and outstanding medical bills. For many grandparents living on a fixed income, leaving behind enough money to cover these expenses feels out of reach. That is where life insurance for grandparents final expense coverage comes in. A small, simplified policy can shield grandchildren and adult children from sudden out-of-pocket costs while giving the policyholder peace of mind. This guide explains how these policies work, who qualifies, how much coverage to choose, and how to request personalized quotes without pressure.
How Final Expense Policies Work for Applicants 50 and Older
Final expense insurance, sometimes called burial insurance or senior life insurance, is a type of whole life policy with a modest death benefit. Most policies range from $5,000 to $40,000, and the application process is far simpler than traditional underwritten life insurance. Applicants who are 50 or older can often qualify with just a few health questions, and many policies skip the medical exam entirely. The death benefit is paid to a named beneficiary, usually an adult child or grandchild, who can use the money for funeral costs, cremation, outstanding debts, or any other final expenses. Because it is whole life coverage, the policy does not expire as long as premiums are paid, and the premium typically stays level for life.
One of the most common misconceptions is that final expense coverage is only for people with serious health problems. In reality, these policies serve a broad range of seniors who simply want a straightforward way to cover end-of-life costs without tying up large sums of money. A grandparent might choose a $10,000 policy to cover a funeral and a small credit card balance, or a $20,000 policy to also leave a little something for grandchildren. The key is that the coverage amount is chosen by the applicant, not dictated by a one-size-fits-all formula. For a deeper look at how specific programs are structured, including AARP life insurance programs from New York Life, you can explore how those options compare to simplified issue policies.
Premiums are based on age, gender, tobacco use, and the coverage amount selected. A healthy 65-year-old woman might pay $30 to $50 per month for $10,000 of coverage, while a 75-year-old man might pay closer to $70 or $80 for the same benefit. These figures are examples, not guarantees, because rates vary by carrier and underwriting. The important takeaway is that final expense policies are designed to be affordable on a fixed income, and many insurers offer premiums that fit within a Social Security budget.
No-Medical-Exam Options and Simplified Eligibility
For many grandparents, the fear of a medical exam is the biggest barrier to getting life insurance. They worry that a health issue from years ago will disqualify them or that the process will be invasive and time-consuming. Simplified issue final expense policies address this directly. Instead of a paramedical exam with blood work and vitals, the application asks a short series of health questions. In many cases, approval can happen within days, and some carriers offer same-day decisions.
Here is what the typical simplified issue process looks like for a grandparent applying for final expense coverage:
- Answer basic personal information: age, height, weight, and tobacco use.
- Complete a short health questionnaire covering conditions like heart disease, cancer, and diabetes.
- Select a coverage amount and beneficiary, often an adult child or grandchild.
- Receive a decision, which may be immediate or within a few business days.
- Pay the first premium, and the policy goes into effect.
Not every health condition leads to a denial. Many carriers offer graded benefit policies for applicants with more serious health histories. With a graded benefit, the full death benefit is not available during the first two or three years; instead, the beneficiary receives a refund of premiums plus interest if the insured passes away during that period. After the graded period, the full benefit applies. This structure allows grandparents with health challenges to still secure coverage and protect their families from funeral costs. The key is to be honest on the application, because misrepresenting health information can lead to a denied claim later.
Simplified eligibility also means that age alone does not disqualify applicants. Many carriers accept new policyholders up to age 80 or even 85, depending on the product. For grandparents who assumed they were too old to qualify for life insurance, a final expense policy can be a realistic and accessible option. The trade-off is that coverage amounts are smaller than traditional term or whole life policies, but that is exactly the point: these policies are sized to cover final expenses, not to replace decades of income.
Setting a Coverage Amount That Covers Funeral and Small Debts
Choosing the right coverage amount is one of the most important decisions a grandparent will make. Too little, and the family may still face out-of-pocket costs. Too much, and the premiums become unnecessarily expensive. The starting point is a realistic estimate of funeral costs. According to the National Funeral Directors Association, the median cost of a funeral with viewing and burial is around $7,800, and that does not include a burial plot, headstone, or cemetery fees. A cremation with a memorial service typically runs $5,000 to $7,000. These figures vary by region and by the choices made by the family.
Beyond the funeral itself, grandparents should consider other final expenses that a policy can cover. Common items include:
- Outstanding medical bills or co-pays from the final months of life.
- Credit card balances or personal loans that could otherwise fall to family members.
- Legal or probate fees associated with settling an estate.
- A small emergency fund for travel or other costs incurred by family members.
Adding these items to the funeral estimate gives a more complete picture. For example, a grandparent with a $7,000 funeral estimate, $2,000 in medical bills, and a $1,000 credit card balance might choose a $10,000 policy. That amount covers the essentials without over-insuring. If the goal is also to leave a small legacy for grandchildren, a $15,000 or $20,000 policy could be appropriate, provided the premium fits comfortably within the budget. The rule of thumb is to prioritize coverage that prevents financial hardship for loved ones, then add a legacy component only if it is affordable.
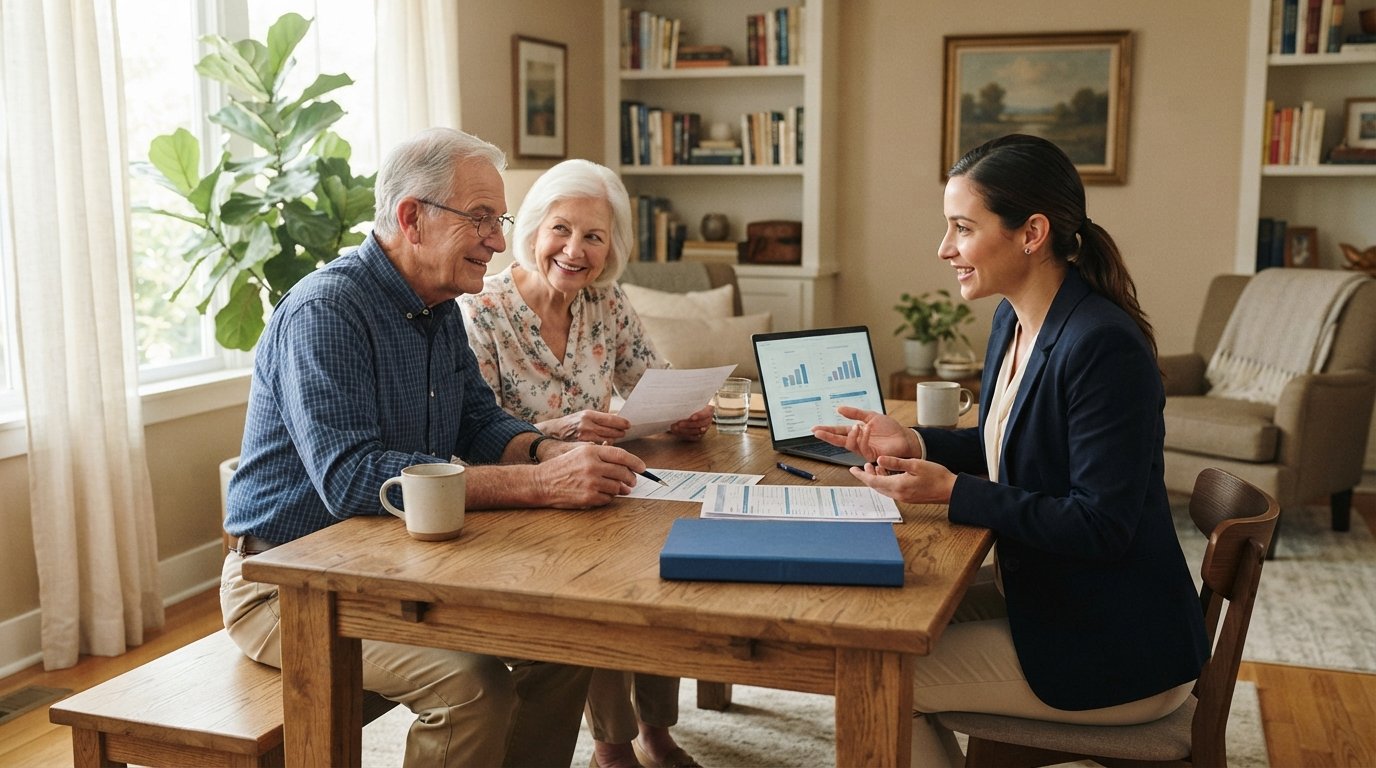
It is also worth reviewing existing coverage before purchasing a new policy. Some grandparents have a small group life policy through a former employer or a union, or a burial policy purchased years ago. These existing benefits can reduce the amount of new coverage needed. A licensed agent can help review current policies and identify any gaps. This is where a service like LifeInsurance-Quote.com can be useful, because it connects consumers with professionals who analyze needs and suggest plans at an affordable cost, rather than pushing a one-size-fits-all product.
How to Request Personalized Final Expense Quotes
The final step is getting quotes from multiple carriers so that a grandparent can compare premiums and benefits side by side. Final expense rates vary significantly from one insurer to another, and the same applicant might see a 30 to 50 percent difference in monthly premium depending on the carrier. Requesting quotes does not obligate anyone to buy, and it does not affect credit scores or health records. The process is designed to be low-pressure and educational.
Here is how to request personalized quotes efficiently:
- Gather basic information: date of birth, height, weight, tobacco use, and a list of current medications.
- Decide on a target coverage amount based on funeral costs and small debts.
- Use a quote-request platform to compare offers from multiple carriers at once.
- Speak with a licensed agent to clarify health questions and beneficiary options.
- Review the policy details, including the graded benefit period if applicable, before signing.
Working with a licensed agent is especially valuable for grandparents who are unsure about which health conditions need to be disclosed or which carriers are most lenient with certain diagnoses. USLifeQuote.com is designed for exactly this purpose: it is a free, no-obligation quote-request and call-connect platform that links consumers with participating third-party insurance professionals. Users enter their ZIP code, age range, and tobacco use, and the platform shows matching insurers for side-by-side comparison. The site does not sell insurance directly, but it simplifies the process of finding an agent who can analyze individual needs and recommend an affordable final expense plan.
One practical tip is to request quotes from at least three carriers. If one insurer declines due to a health condition, another may offer a graded benefit policy or a simplified issue product with different underwriting guidelines. Grandparents should also ask about the premium payment options: monthly bank drafts are common, but some carriers offer quarterly or annual payment discounts. Finally, it is important to name a beneficiary and keep that designation up to date. A grandchild can be named as a beneficiary, but if the grandchild is a minor, a guardian or trust arrangement may be needed to manage the funds until the child reaches adulthood.
Planning ahead with life insurance for grandparents final expense coverage is an act of consideration for the family. It spares grandchildren and adult children from scrambling to cover funeral costs during an already difficult time, and it gives the policyholder control over how final expenses are handled. With simplified issue policies, no-medical-exam options, and flexible coverage amounts, most grandparents aged 50 and older can find an affordable plan that fits their budget. The key is to start the conversation early, compare quotes from multiple carriers, and work with a licensed professional who can guide the decision without pressure. Taking that step today can provide lasting peace of mind for the entire family.